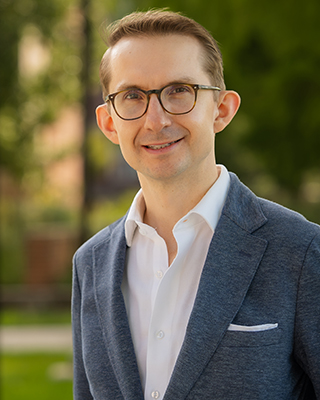
Josh Mollner, a self-proclaimed “math nerd” who has a dual bachelor’s degree in economics and mathematics from Notre Dame, developed an interest in market design and market microstructure research because it comes at the sweet spot of theory and application.
“I like working in the language of math but also connecting it to stuff that people should care about and that might matter for policy,” Mollner said. “I love it when a model teaches you something that surprises you and would have been hard to see otherwise.”
He brings that mindset to his new position as associate professor of finance at Gies College of Business.
Mollner earned a PhD in economics from Stanford in 2015, working under one of the most respected economic minds in the world, Paul Milgrom, an expert in game theory, who was the co-recipient of the 2020 Nobel Prize in Economic Sciences “for improvements to auction theory and inventions of new auction formats.”
“It was a cool experience to be able to learn from him, and being around him shaped who I am as a scholar,” Mollner said.
A native of Minnesota, Mollner returned to the Midwest following his time at Stanford and has spent the last 10 years at Northwestern University’s Kellogg School of Management, where his research has focused on financial market design, including both on-exchange and off-exchange trading.
“People used to trade in person. Think about the floor of the New York Stock Exchange. That takes time,” Mollner said. “Now we have computers that are automated and react super-fast, to the point where microseconds can matter. What does this additional speed mean for transaction costs? How liquid are markets? How informative are prices? How well is capital being allocated to its most productive uses?”
Mollner explored the answers to some of those questions in a 2020 paper titled “High-Frequency Trading and Market Performance,” which was published in The Journal of Finance. The paper used a theoretical model of high-frequency trading to determine the implications of these faster speeds.
The model suggested that faster speeds make markets more liquid, tightening bid-ask spreads and lowering trading costs, in line with empirical evidence from other studies.
“The downside that the model predicts is that these faster speeds make prices less informative, so maybe there is a trade-off there,” Mollner said. “We tried to look at whether there are ways to tweak the trading mechanism that exchanges are using in a way that might handle this trade-off better.”
Mollner’s work has caught the attention of the SEC, which invited him to present his work. He also submitted a comment letter when it was considering some rule changes.
Another area of Mollner’s research focuses on how retail orders are handled. Today, orders from retail brokerages like Charles Schwab or Robinhood are often segmented from those coming out of other institutions, meaning that as much as 95 percent of the retail order flow isn’t routed to stock exchanges like the NYSE. Instead, it is routed directly to market-making firms, which actually means better prices than if it were routed to exchanges.
“I think this is an interesting space,” Mollner said. “If we are going to segment the orders of different trader types, what are the implications of segmentation? There are a lot of questions in that space that are underexplored.”
Mollner developed a model to explore whether policymakers in the U.S. equity market (i.e., the Securities and Exchange Commission) could design intelligent rules that influence segmentation. That research led to his 2024 paper titled "Miixology: Order flow segmentation design."
Besides his research, Mollner earned the 2022 Sidney J. Levy Teaching Award at Northwestern. He especially enjoyed teaching a class on the MBA track called Competitive Strategy.
“I thought that was a fun class to teach because there was actually a lot of theory,” Mollner said. “However, at a business school, you can’t just teach theory for its own sake; you have to connect it to things that matter. What I liked about that course was that it connected some of these abstract theories to tangible cases. That allowed me to convince students that these theories were useful in understanding the real world and helping make smart business decisions.”
Mollner is excited to bring his theoretical work to Gies Business and draw on the complementary empirical expertise of Gies scholars like Neil Pearson and Dmitriy Muravyev.
“Gies is a great environment for research, with all the support and resources needed for doing high-quality work,” Mollner said. “I hope to become even more strongly regarded as a top scholar in my area of finance. I’m also excited to start collaborations with some of my new colleagues and perhaps branch out to other areas of finance. When you have so many highly respected researchers in one place, you never know when a simple conversation will spark your next big idea.”